Market intelligence

Decide with data,
not assumptions.

Clear, actionable market reports: verified data, competitive analysis and expert judgement to decide with solid ground.

Rigorous · Objective · Actionable
87published reports
PDFfree samples
PDF interiorPDF interiorPDF interior
Inside the reportPages, charts and verifiable sources
01

Know your market

We provide market analysis that removes the guesswork. Built from verified, triangulated sources, with every figure cited and its confidence level stated. So you can act on certainties, not assumptions.

02

Know your competition

We go beyond «the market is fragmented». We map every brand by name: how many locations it has, where it operates and its real size. Know the ground before you step on it.

03

Know your next move

We don't stop at the data. Every report arrives with readings and recommendations to decide where, how and against whom to compete. Your next move starts here.

Catalogue

Available reports

Each report turns hard-to-compile data into a direct analysis: a real competitive map, economics and location-level opportunity.

All reports

Full catalogue by market, country and vertical.

Premium coffee vending machines in Spain · Decision report on sites, fleet size, route economics, the legal framework and the return per machinePDF interior
Available
2026 editionFree sample

Premium coffee vending machines in Spain · Decision report on sites, fleet size, route economics, the legal framework and the return per machine

Decision report for the owner-operator —a small business or a solo entrepreneur— weighing whether to buy premium coffee machines, sign site agreements and run the route at their own risk in Spain. This is not a vending manual: it is the calculation of whether that decision returns the money. Five archetypes —scattered small and mid-sized offices, a single large corporate headquarters, a public site awarded by tender, a premium coffee corner and a service subsidised by the employer— run through one single economic engine: NPV, IRR, payback, a sensitivity tornado and a fleet-size matrix, with the owner's gross salary paid before the cash flows are discounted and terminal value set at the residual value of the hardware, never at a multiple of earnings. The report turns on a distinction the trade blurs: cost per cup scales with consumption and cost per visit does not, so what decides the outcome is not the margin per cup but how many service visits each machine demands and who makes them. It covers the real cost build-up per cup at 2026 Spanish B2B list prices, the site commission measured against the cost of the beans, the thresholds for accepting, testing or rejecting a location —including the freshness threshold almost nobody measures—, the legal framework verified rule by rule (the Spanish food business register, the IAE business tax heading 647.5 with its two rates, the 10 % IVA — Spanish VAT — on coffee against 21 % on soft drinks, verifiable invoicing and the free-loan machine contract), the public channel with its price capped by the tender and its fixed fee per machine, telemetry audited against its own sources, maintenance, and an adversarial review that builds the case against the report's own verdict. With a traceability register of 149 assumptions, each with its source, its date and its confidence grade. Scope: Spain. 2026 data · Edition 7.

€990
single licence · PDF
View details →
Bottled cold brew in Spain · Decision report on formulation, microbiological safety, shelf life, manufacturing and the chilled channelPDF interior
Available
2026 editionFree sample

Bottled cold brew in Spain · Decision report on formulation, microbiological safety, shelf life, manufacturing and the chilled channel

Decision report for the roaster, drinks brand or small investor weighing whether to bottle cold brew in Spain. The question that governs everything is not «do people like the product?», but «which product, with which preservation treatment, in which pack and for which channel — and is it worth it?». Three archetypes —the roaster who bottles and sells through their own channel, the brand without a plant that manufactures through a co-packer for the chilled retail shelf, and the bag-in-box concentrate for the hospitality trade— run through the same financial engine: NPV, IRR, break-even, a commercial ramp-up and a sensitivity matrix, with working capital and the co-packer's minimum order quantity inside the discounted cash flow, not in a footnote. It covers the microbiological safety file of a low-acid food that tastes mild (pH, water activity, spore formers, Listeria and the regime that tightened in July 2026), three preservation routes compared on their real availability in Spain and not only on their cost, the effective selling window against the use-by date, the physical compatibility between pack and process, the legal and labelling framework (RGSEAA — the Spanish food business register, legal name, caffeine warning, the deposit return scheme and the IVA — Spanish VAT — rate verified against the article of Law 37/1992), the cold chain modelled per delivery, and an external adversarial review that invalidated the report's first version. Scope: Spain. 2026 data · Edition 7.

€3,499
single licence · PDF
View details →
Coffee capsule recycling in the EU · A decision report for an operator-investorPDF interior
Available
2026 editionFree sample

Coffee capsule recycling in the EU · A decision report for an operator-investor

A decision report for the waste operator or the investor weighing whether to BUILD a business collecting and treating used coffee capsules in the European Union. The question that orders everything is not «what is the recovered aluminium worth?» but «who pays the cost of bringing that capsule —wet, light and scattered— to the plant?». Five decision archetypes run through the same financial engine (mass balance, NPV, gate-fee break-even, sensitivity tornado), the physics of the capsule gram by gram, the PPWR's EPR framework with its exact dates, the real competitive map (Nespresso, Podback, CITEO, Austria) and an adversarial review briefed to destroy the thesis. Scope: harmonised EU, Spain as the test case. 2026 data · Edition 7.

€3,499
individual licence · PDF
View details →
Private-Label Coffee: the own-brand buyer's decisionPDF interior
Available
2026 editionFree sample

Private-Label Coffee: the own-brand buyer's decision

A decision report for whoever buys or launches a private-label coffee —retailer, D2C brand or horeca operator— and needs to know, format by format, where the margin fits. It resolves, with the real arithmetic of the value split (from shelf price to net price to the maker's margin, with rebate and supplier approval), a GO/NO-GO verdict by buyer archetype: ground, capsule and instant across the European Union, with the unit economics, the sensitivity matrix, the map of makers and co-packers, the legal framework (EUDR, labelling, packaging) and an adversarial review that attacks its own thesis. Edition 7.

€990
individual licence · PDF
View details →
Mercadona's Total Quality ModelPDF interior
Available
2026 editionFree sample

Mercadona's Total Quality Model

An analysis for anyone running a chain or a mid-sized retail business who has ever thought "we should do what Mercadona does." This is not a company biography: it is a reverse-engineering of the model, piece by piece, to separate what a retailer can replicate without Mercadona's size from what stays anchored to scale. With the real arithmetic of margin and turnover, the supplier system as it is today, the labour pillar with its two sides as verified in the courts, a benchmark against Consum, Dia, Lidl and Trader Joe's, and a replicability verdict component by component. Edition 7.

€990
individual licence · PDF
View details →
Inditex's Global Business ModelPDF interior
Available
2026 editionFree sample

Inditex's Global Business Model

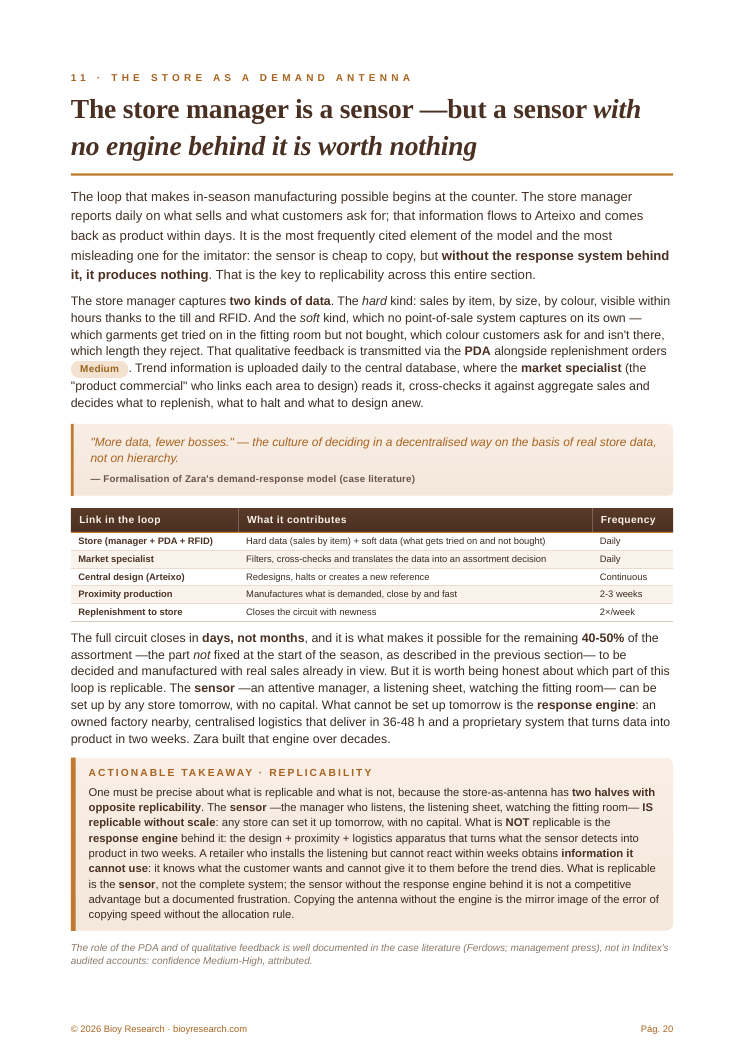
An analysis for anyone running a fashion brand or a growing chain who has ever thought "we should operate like Zara." This is not a company biography: it is a reverse-engineering of the system, lever by lever, to separate what another brand can replicate without Inditex's size from what stays anchored to scale. With the real arithmetic of margin and working capital, proximity sourcing as it actually is today —and its expiry date—, the supply chain with both sides verified, a benchmark against H&M, Shein, Primark, Uniqlo and Mango, and a quantified model that puts numbers on which product types justify copying deferred inventory. Edition 7.

€990
individual licence · PDF
View details →
Mikel Coffee: franchise due diligencePDF interior
Available
2026 editionFree sample

Mikel Coffee: franchise due diligence

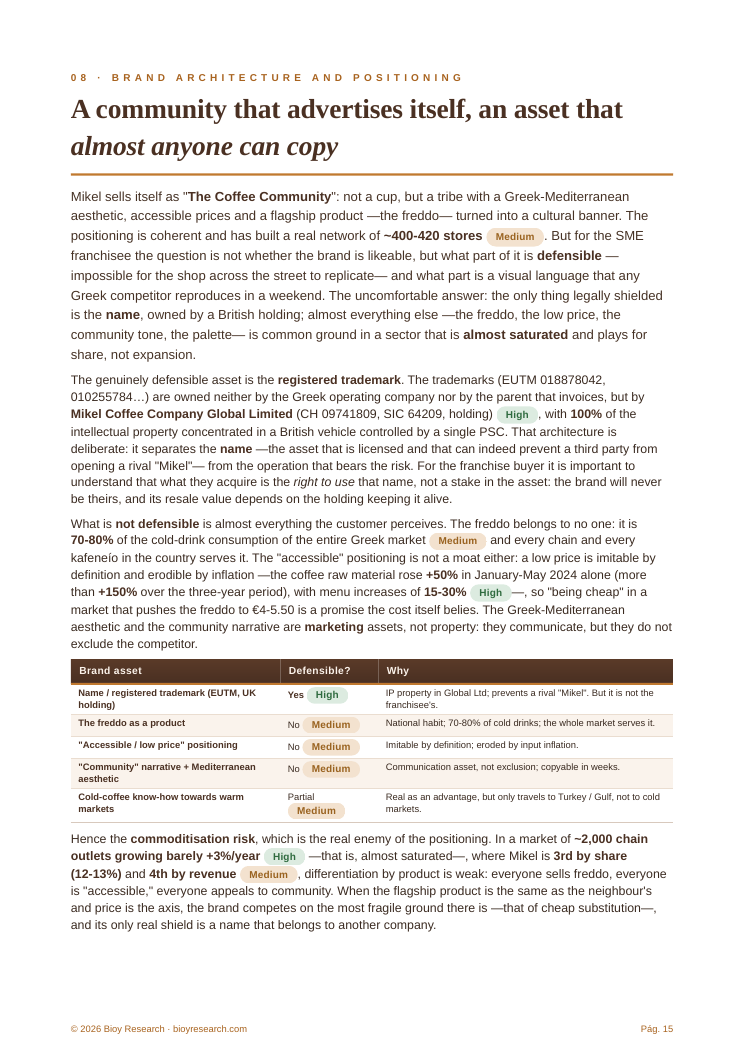
A decision report for the SME with the money on the table, asking whether buying a Mikel Coffee franchise —or opening several— recovers the capital or merely pays a salary. This is not a brand brochure: it is the forensic file with which you sign or walk away, with the economics of a typical store modelled on 2026 Greek costs, the owner's shadow salary booked into the accounts, the real figures of the Greek parent company, the network of ~418 stores reconciled country by country against what the brand advertises, the franchisor's three income streams —including the coffee the franchisee is obliged to buy—, and a verdict for each option. Stated and proven upfront: in the base case this is self-employment, not an investment. Edition 7.

€3,499
individual licence · PDF
View details →
Coffee e-commerce: selling coffee online in SpainPDF interior
Available
2026 editionFree sample

Coffee e-commerce: selling coffee online in Spain

A decision report for the digital entrepreneur who wants to build an online coffee brand without owning a roastery, buying the roast in from a third party. The thesis: the order's margin is not the problem; the customer who buys only once is. The report resolves, with the real arithmetic of the order line by line, a decision matrix on acquisition cost and repeat-purchase frequency, a dated audit of Spanish stores, the taxonomy of eleven distinct business models, the verified legal and tax framework, and an adversarial review that attacks the report's own thesis, exactly which box your case falls into. Edition 7.

€990
individual licence · PDF
View details →
Monthly coffee subscription: the roaster's subscriber clubPDF interior
Available
2026 editionFree sample

Monthly coffee subscription: the roaster's subscriber club

A decision report for the roaster who already produces and sells, and is considering opening a subscription club. The thesis starts from official data: the average Spanish household consumes 156 g of pure roast coffee a month and the market's entry plan ships 271 g. The report resolves, with cohort economics calculated shipment by shipment, a grid of 60 combinations of size, cadence and household profile; the shipping-cost staircase by weight band, which decides which plan makes money; a dated audit of five Spanish operators; the legal framework verified in the Spanish official gazette —renewal notice and right of withdrawal—; the break-even with and without the owner's time; and an adversarial review that attacks the report's own thesis, exactly which box your case falls into. Edition 7.

€990
individual licence · PDF
View details →
How to choose a European postgraduate degree after PsychologyPDF interior
Available
2026 editionFree sample

How to choose a European postgraduate degree after Psychology

Cost, employability, return and risk of each option, for the Psychology graduate who is not yet sure about their specialisation. The thesis: the postgraduate degree is not the decision; the LICENCE TO PRACTISE is. Decide what you want to be allowed to do, check the programme actually grants it, and only then look at prestige, country and price. A decision framework with 3 worked archetypes, the recognition-and-licensing map (EuroPsy, MPGS/PIR, GZ/BIG, Approbation, DClinPsy, OPP), 26 career paths, in-depth country files for 6 countries plus 11 second-tier ones, and a financial return model with simulator, sensitivity analysis and an FMEA risk matrix. Edition 7.

€349
individual licence · PDF
View details →
Entering Argentina · Professional espresso machinesPDF interior
Available
2026 editionFree sample

Entering Argentina · Professional espresso machines

The entry file into Argentina for a European maker of traditional espresso machines (1, 2 and 3 groups). The finding that orders everything else: it is not "don't enter Argentina", it is "don't enter with THAT machine". The border is one of product, not price. There are two markets: the traditional bar is a NO-GO — four Argentine factories (La Valente since 1955, Lainex, RILO, Monaco) sell a 2-group machine at US$ 3,959, with local parts and service, while the Spanish machine lands at US$ 7,754 — and the specialty café is a conditional GO — it pays US$ 6,000-30,000 and zero out of six fit a domestic machine. The question that decides it: does your machine have PID and a multi-boiler? Five entry models run through the same financial engine (NPV, break-even, scenarios, tornado), the comodato quantified as a premium channel, and an adversarial review by four experts that DESTROYED the flagship finding: the supposed "category E" of the EU-Mercosur deal turned out to be false. 2026 data · Edition 7.

€3,499
single licence · PDF
View details →
Kosher Certification · A Decision Report for an Exporting ManufacturerPDF interior
Available
2026 editionFree sample

Kosher Certification · A Decision Report for an Exporting Manufacturer

A decision report for a food-and-ingredient manufacturer weighing kosher certification for export. The question that orders everything is not "how much more will I sell?" but "which specific account closes to me without the symbol, and what does it cost to certify MY plant?". The kosher symbol is a B2B channel-access requirement, not a premium: it rarely lifts the price, but without it you are shut out. Four decision archetypes run through the same financial engine (NPV, break-even, a sensitivity tornado, scenarios), the map of certifiers (OU, KLBD, the Chief Rabbinate) chosen back-to-front from the buyer, the complexity by product category, and an adversarial review briefed to destroy the thesis. Scope: the US, Israel and the EU. 2026 data · Edition 7.

€3,499
single licence · PDF
View details →
Coffee distribution to the hospitality trade in Spain · Decision report on setting up a distributorPDF interior
Available
2026 editionFree sample

Coffee distribution to the hospitality trade in Spain · Decision report on setting up a distributor

A decision report for the entrepreneur or small business weighing up whether to set up a coffee distribution business serving bars and restaurants in Spain. The question that orders everything is not "can I win customers?" but "does this business pay a return on the capital I am about to put in, or does it merely pay me a wage?". Five business models — multi-brand with no assets, exclusive distributor with loaned equipment (comodato), own-label coffee under the distributor's brand, speciality coffee specialist, and buying an existing book of accounts — all run through the same financial engine: NPV, IRR, break-even and a sensitivity tornado, with the owner's market salary deducted before any talk of profit. It includes the real funnel behind the hospitality census (from 235,623 venues down to those you can genuinely win), the consumption threshold below which an account destroys margin, the profit and loss of a single bar line by line, the full loaned-equipment cycle modelled by cohorts, the route density that sets the minimum viable scale, the case law on exclusive supply contracts, and an eight-round adversarial review that corrected 34 errors in the report itself. Scope: Spain. 2026 data · Edition 7.

€3,499
single-user licence · PDF
View details →
Artisan coffee roastery in Spain · Decision report on setting up a roasting plantPDF interior
Available
2026 editionFree sample

Artisan coffee roastery in Spain · Decision report on setting up a roasting plant

Decision report for the entrepreneur or small business weighing whether to set up an artisan coffee roastery in Spain. The question that governs everything is not «do I know how to roast?», but «does the business pay back the capital I am about to put in, or does it just pay me a salary?». Four archetypes —micro-roastery with local sales, digital brand with its own plant, B2B production for the hospitality trade, and private label for third parties— run through the same financial engine: NPV, IRR, break-even and a sensitivity tornado, with the owner's market salary deducted before any talk of profit. It covers the full conversion chain (green kilo → roasted → sellable → net revenue), the real industrial cost per kilo against the maquila (contract roasting) rate, the machines lent out under comodato (free loan of an espresso machine tied to an exclusive supply contract) that nobody budgets for, the legal, food-safety and tax framework (RGSEAA — the Spanish food business register, APPCC — the Spanish HACCP food-safety plan, IVA — Spanish VAT, RETA — the Spanish self-employed social security scheme, Impuesto de Sociedades — Spanish corporate income tax, from 2027) and an adversarial review briefed to destroy the thesis, which pulled a fifth planned archetype out of the report. Scope: Spain. 2026 data · Edition 7.

€3,499
single licence · PDF
View details →
Organic and fairtrade coffee: the decision file of an EU brandPDF interior
Available
2026 editionFree sample

Organic and fairtrade coffee: the decision file of an EU brand

Written for the board of an EU SME coffee brand or roaster — Spain as the lead market — that buys green coffee and must decide whether to launch an organic range, a fairtrade range, both at once or neither. Not an overview of sustainable coffee: it is the folder on which certification is approved or rejected, with all four routes settled through one engine.

€3,499
View report
Premium single-origin coffee: the sourcing decision of a Spanish roasterPDF interior
Available
2026 editionFree sample

Premium single-origin coffee: the sourcing decision of a Spanish roaster

Written for the owner of a Spanish specialty roasting SME — 20 to 150 tonnes a year, deciding alone — weighing whether to build a single-origin range and with which sourcing model. Not a survey of the specialty scene: it is the file on which green coffee purchasing is committed or refused, with five sourcing archetypes settled through one engine and the counterfactual of staying with blends held throughout.

€3,499
View report
Rainforest Alliance Certification in Coffee · A Decision Report for an EU BrandPDF interior
Available
2026 editionFree sample

Rainforest Alliance Certification in Coffee · A Decision Report for an EU Brand

A decision report for an EU coffee brand or manufacturer weighing whether to certify its chain and put the Rainforest Alliance seal on the pack. The question that orders everything is not "will I sell more?" but "is the seal shelf access, a consumer premium, or a sunk cost for MY chain?". In mainstream coffee the seal rarely lifts the price: it is a listing requirement that opens — or does not close — the account with the retailer. Four decision archetypes run through the same financial engine (NPV, IRR, break-even, a sensitivity tornado), the real cost of the seal (per-kilo royalty, traceability, audit), what it guarantees and what it does not against EUDR and greenwashing, the market files by country and channel, and an adversarial review briefed to destroy the thesis. Scope: the EU. 2026 data · Edition 7.

€3,499
single licence · PDF
View details →
Halal Certification · A Decision Report for an EU Exporting ManufacturerPDF interior
Available
2026 editionFree sample

Halal Certification · A Decision Report for an EU Exporting Manufacturer

A decision report for an EU food-and-ingredient manufacturer (based in Spain) weighing halal certification for export. The question that orders everything is not "how much more will I sell?" but "in which destination is the mark mandatory by law, which agency does that customs authority recognise, and what does it cost to adapt MY plant?". Halal is not a premium: in Indonesia it is mandatory by law and in the Gulf it is mandatory for any animal product; without the right mark the container does not enter. Five decision archetypes run through the same financial engine (NPV, IRR, break-even, a sensitivity tornado, scenarios), the recognition map across more than 400 agencies —the expensive mistake is not getting certified, it is doing so with the one the destination customs authority does not recognise—, the complexity by product category, the separate case of ritual slaughter, and an adversarial review briefed to destroy the thesis. Scope: Indonesia, the Gulf (GCC), Malaysia, Türkiye and the EU/US. 2026 data · Edition 7.

€3,499
single licence · PDF
View details →
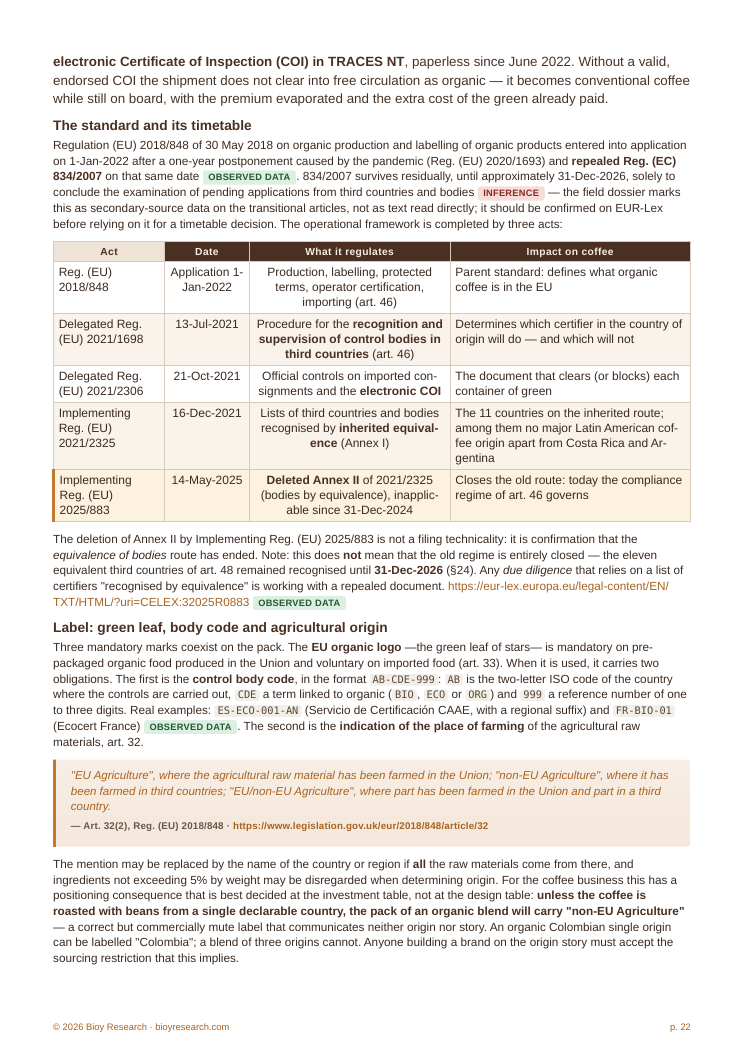
Organic Coffee in the EU · An Investment Decision ReportPDF interior
Available
2026 editionFree sample

Organic Coffee in the EU · An Investment Decision Report

Investment due diligence for the management or investment committee of an agri-food company weighing capital in the certified organic coffee chain into the European Union. The question that orders everything is not «how fast is the organic market growing?», but «at which link does the seal actually leave money, and against what is it compared?». Three archetypes —converting production at origin, buying certified green and roasting, certifying an existing plant— plus a format variant, all run through the same financial engine (NPV, IRR, payback, lever bridge, break-even and tornado), with the reproducible model delivered alongside the report. Covers the Reg. (EU) 2018/848 framework and compliance-route imports with a COI in TRACES NT, the EUDR (Reg. 2023/1115) with its current dates and cost, the PPWR for the capsule format, the gap between certified volume and volume sold at a premium, real willingness to pay, and an adversarial review briefed to destroy the thesis. Currency EUR. 2026 data · Edition 7.

€3,499
single licence · PDF
View details →
AI Audiovisual Production & Advertising · Spain 2026PDF interior
Available
2026 editionFree sample

AI Audiovisual Production & Advertising · Spain 2026

Opportunity due diligence for a small or mid-sized audiovisual production company or agency (10-40 people) in Spain weighing whether to capture value with generative AI. The question that orders everything is not «how much does AI speed up production?», but «on which type of piece does the cost per approved piece actually fall, and against what is it compared?». Five archetypes —augmented studio, AI-native production house, automation for agencies, self-service SaaS platform, and vertical specialist— all run through the same economic engine (NPV, IRR, maximum cash exposure, break-even, tornado and base, adverse and severe scenarios), with the reproducible model delivered alongside the report. The finding that orders the thesis: the saving is not in generating, it is in the cost per approved piece, and it is a spread by type of piece —very large on product video and versioning, and evaporating on the brand hero spot. Covers the AI Act (Reg. (EU) 2024/1689) framework with the deepfake transparency of Art. 50, the intellectual property of AI output, image and voice rights (Organic Law 1/1982), the copyright indemnity offered by each tool, and Spanish taxation, plus an adversarial review briefed to destroy the thesis. Currency EUR. 2026 data · Edition 7.

€3,499
single licence · PDF
View details →
Vaca Muerta 2026-2035 · Entering as a supplier to the operatorsPDF interior
Available
2026 editionFree sample

Vaca Muerta 2026-2035 · Entering as a supplier to the operators

Market-entry due diligence for the board of an industrial or services company weighing whether to sell to Vaca Muerta operators. This is not a report about investing in oil: the reader does not drill, the reader SELLS to those who do. The question that orders everything is not «how fast is the basin growing?» but «how much of that spend is genuinely addressable by a foreign entrant, and at what margin?». The announced-investment headline is discounted step by step down to the spend a supplier can actually invoice; Neuquén's local-content law is read against the official text —including the arithmetic that caps a foreign-owned company—; and four entry archetypes run through the same economic engine (NPV, IRR, gross-margin threshold, working capital, utilisation break-even). With an adversarial review, four documented rounds of external audit and the evidence gaps declared. Currency USD. 2026 data · Edition 7.

€3,499
single licence · PDF
See details →
RIGI Argentina · An Investment Decision Report for a FundPDF interior
Available
2026 editionFree sample

RIGI Argentina · An Investment Decision Report for a Fund

An investment due diligence for the committee of an infrastructure or natural-resources fund weighing whether to finance a large-scale Argentine project under RIGI (the Large Investment Incentive Regime). The question that orders everything is not "how much does the incentive yield?" but "is this project investable, how does the product leave the country, and who buys it?". RIGI-eligible is not the same as investable: approval is an act about the vehicle, not about feasibility. Four investment archetypes run through the same financial engine (NPV, IRR, DSCR, break-even, project-finance waterfall), RIGI read as a 30-year FX-and-stability regime rather than a corporate-tax one, sovereign risk with its track record of arbitral awards —formal law is not effective protection—, the constraint that decides (evacuation and offtake, not the incentive), and an adversarial review briefed to destroy the thesis. Scope: lithium, Vaca Muerta and evacuation infrastructure. Currency USD. 2026 data · Edition 7.

€3,499
single licence · PDF
View details →
Sports Supplements · A Decision Report for Launching an Own Brand in the EUPDF interior
Available
2026 editionFree sample

Sports Supplements · A Decision Report for Launching an Own Brand in the EU

A decision report for the founder or investment committee weighing the launch of an own-brand sports supplement line in the EU (based in Spain), manufactured through a co-packer and sold across D2C, marketplace, retail and gyms. The question that orders everything is not "which product is trending?" but "what am I legally allowed to say, what does the tub really cost, and which channel leaves me a margin once its fees are taken out?". Five launch archetypes run through the same financial engine (NPV, IRR, payback, break-even, tornado, scenarios), the ingredient–goal–evidence–dose matrix built on the AIS and IOC frameworks, the claims straitjacket verified against the full EU Register of Regulation 1924/2006, the anti-doping exposure under strict liability, the tub-by-tub cost with official rate cards, and an adversarial review that changed the verdict —published with its before and after. 180 pages · 2026 data · Edition 7.

€3,499
single licence · PDF
View details →
Entering Brazil · Professional espresso machinesPDF interior
Available
2026 editionFree sample

Entering Brazil · Professional espresso machines

The entry file into Brazil for a European maker of traditional espresso machines (1, 2 and 3 groups). The finding that orders everything else: the import duty on your machine is 20% — or 0% — and what separates the two is a filing worth R$ 1.58 million. But only if your boiler falls inside a paragraph written by a civil servant: the one-group machine does not fit the spec sheet and pays the 20%. Five entry models run through the same financial engine (NPV, IRR, break-even, scenarios), the Brazilian comodato quantified for the first time — "free" is the most expensive way to have a machine — and an adversarial review by four experts briefed to destroy the thesis: they found 26 objections and the report was rewritten. 2026 data · Edition 7.

€3,499
single licence · PDF
View details →
Spain EV Charging Market Entry Playbook 2026PDF interior
Available
2026 editionFree sample

Spain EV Charging Market Entry Playbook 2026

The Spanish EV charging market read as an entry decision by a foreign charge point operator, an infrastructure fund or a fleet-charging operator. Eight business models run through the same financial engine: one creates value, seven destroy it. The thesis is uncomfortable — the enemy is not Spain, it is direct current: hold the fleet and the kilowatt-hours constant and AC returns 14.1% IRR while DC returns between −4.7% and +2%. And the whole business fits inside four cents: the one asset that works needs a price above €0.36/kWh, and the price Spanish fleets are actually signing is €0.32/kWh — extracted from the technical evaluation report of a signed Ministry of Defence framework agreement. Grid access, permitting, tariffs, city and corridor prioritisation, line-by-line CAPEX/OPEX benchmarks, entry routes and partnerships, 8 due-diligence checklists and 5 ready-to-use templates. 2025–2026 data · Edition 6.

€3,499
individual licence · PDF
View details →
Doing Business in the UAE: Market Entry ReportPDF interior
Available
2026 editionFree sample

Doing Business in the UAE: Market Entry Report

A market-entry decision manual for foreign companies that want to sell, invest, hire, set up an entity, import/export or find partners in the United Arab Emirates. Written for five buyer archetypes: exporters, SaaS/digital and professional services, manufacturers looking for distributors, retail/franchise, and investors/family offices. With a reproducible Market Entry Score across 8 weighted pillars (UAE 64/100, benchmarked against Singapore 76, Ireland 71, Saudi Arabia 58 and Qatar 55), a cost-to-enter / cost-to-operate model with a 2D decision matrix and a calculated tornado (year-1 all-in: AED 87k sell-from-abroad · AED 262k free-zone lean · AED 848k mainland LLC · AED 1.29m DIFC/ADGM), and a 90-day entry plan by archetype. Covers the mainland vs free zone vs offshore decision (100% foreign ownership since 2021; the QFZP 0% rate is conditional and forfeitable), the Commercial Agencies Law trap, corporate tax 9% / VAT 5% / 15% DMTT, labour costs, gratuity and Emiratisation, the bank account as the real gate (banking is the worst-scoring pillar: 42/100), customs, ICV and government tenders, the top-10 concrete entry plays and the emirate map (Dubai, Abu Dhabi, Sharjah, Northern Emirates). 2025–2026 data · Edition 5.

€299
individual licence · PDF
View details →
Premium Children's Enrichment Studios: Germany Market Entry ReportPDF interior
Available
2026 editionFree sample

Premium Children's Enrichment Studios: Germany Market Entry Report

Germany's premium children's enrichment sector read as a market-entry decision — music, art, STEM/coding/robotics, languages, premium sport & movement, drama and early-development, across recurring classes, memberships, camps, birthday parties and franchises. A market with no single audited figure (triangulated at ~€2–4bn) on a shrinking demographic base (654,241 births in 2025, the lowest since 1946), with no national cross-format brand and whitespace in physical STEM/coding. With the regulatory-tax spine (per-discipline USt under §4 Nr. 21 — music/languages/coding exempt vs. swimming/riding/leisure at 19%; the 2028 Scheinselbständigkeit/Herrenberg time-bomb; child protection), a prime classroom-hour capacity engine, economics by format, the Speckgürtel geographic arbitrage and an Edition-5 decision simulator with break-even at 93 enrolments. 2024–2026 data · Edition 5.

€299
individual licence · PDF
View details →
EUDR compliance for importers of coffee, cocoa and chocolate · Edition 5 2026PDF interior
Available
2026 editionFree sample

EUDR compliance for importers of coffee, cocoa and chocolate · Edition 5 2026

An operational playbook to comply with Regulation (EU) 2023/1115 (EUDR): traceability, geolocation, the DDS in TRACES, risk assessment and mitigation, country benchmarking, penalties and timeline, with a multi-country focus on Spain, Germany, France and Italy. Edition 5.

€299
individual licence · PDF
View details →
Artisan bakeries and premium bakery cafés in Spain · Market study 2026PDF interior
Available
2026 editionFree sample

Artisan bakeries and premium bakery cafés in Spain · Market study 2026

An investment market study for artisan bakeries, sourdough and premium bakery cafés in Spain: real competition by neighbourhood, prices, five formats compared, unit economics and a GO/NO-GO decision simulator. Edition 5.

€299
individual licence · PDF
View details →
How to Open a Matcha Bar in Spain · Practical Guide 2026PDF interior
Available
2026 editionFree sample

How to Open a Matcha Bar in Spain · Practical Guide 2026

A practical opening guide, not a market study: how to set up a single-product matcha bar in Spain, with retail and direct-to-consumer (DTC) as a second revenue line. It is cheap to build (no espresso machine, saving €6,000–15,000), but holding the margin is not (matcha food cost 25–40% vs 15–25% for coffee, and rising with the supply crisis). Concept, licences, tax, matcha importing, bar economics, staffing and brand, with a GO/NO-GO decision simulator (§20·A). Edition 5.

€299
individual licence · PDF
View details →
The coffee roasting business in France · 2026 StudyPDF interior
Available
2026 editionFree sample

The coffee roasting business in France · 2026 Study

A market and investment study of the coffee roasting business (torréfaction) in France: B2B manufacturing, not a coffee shop. Buy green coffee, roast it and sell beans or ground to hospitality (CHR), shops, direct-to-consumer (DTC) and private label. The thesis: you don't win by roasting, you win in the sales channel and the mix; green coffee is 60–75% of cost and is in a historic crisis (arabica +190% since 2023). Focus format: the specialty micro-roaster (a 5–15 kg roaster), with roastery-café, private-label and industrial variants. The tax finding: roasted coffee in a bag is taxed at 5.5% VAT in France (Art. 278-0 bis CGI), not 20%, and the tariff favours roasting in France (green coffee 0% vs imported roasted 7.5%). Break-even 1,372 kg/month, GO ≥ 2,000 kg/month, capital from €85,000; the real risk is working capital. ED5 decision simulator (§20·A). 2026 data · Edition 5.

€299
individual licence · PDF
View details →
How to open a coffee shop in the UK · Practical guide 2026PDF interior
Available
2026 editionFree sample

How to open a coffee shop in the UK · Practical guide 2026

A practical, operational playbook, not a market study: the steps, the real numbers and the decision filters to open one coffee shop in the UK. Planning (Use Class E: convert an ex-shop with no permission) and the two deal-killers (external flue and pavement licence); tax (the £90k VAT cliff, eat-in 20% vs cold-takeaway 0%, business rates, Corporation Tax); money (build CAPEX £110k–150k, total cash to open safely £145k–245k+, break-even ~130–151 covers/day, a model £320k P&L at ~9% net, NLW £12.71/hr). The Edition 5 highlight is a decision simulator (§20·A) with a tornado of 6 levers and a GO/ALERT/NO-GO matrix. City drill-down (London, Manchester, Birmingham, Bristol) and England/Scotland/Wales/NI divergences. 108 pages, 96 sections and 33 quotes from UK operators · Edition 5.

€299
individual licence · PDF
View details →
How to Open a Coffee Shop in Italy · Practical Guide 2026PDF interior
Available
2026 editionFree sample

How to Open a Coffee Shop in Italy · Practical Guide 2026

A practical, operational playbook, not a market study: the steps, the real numbers and the decision filters to open a bar or caffetteria in Italy. The three models (traditional bar, specialty and take-away), the professional requirement (SAB) you need before the money, the zone tutelate where you cannot open, the SCIA and the comodato d'uso, the VAT that depends on where it is consumed, real CAPEX and P&L, break-even and a decision simulator with a GO/NO-GO verdict. Milan · Rome · Turin · Bologna. 115 pages, 90 sections and 15 industry voices · Edition 7.

€299
single licence · PDF
View details →
How to Open a Coffee Shop in Greece · Practical Guide 2026PDF interior
Available
2026 editionFree sample

How to Open a Coffee Shop in Greece · Practical Guide 2026

A practical, operational playbook, not a market study: the steps, the real numbers and the decision filters to open a coffee shop in Greece. The comodato (χρησιδάνειο) that makes opening cheap but takes the margin with it, the δήμος that decides more than the State, the four doors of the premises, the ΦΠΑ that depends on where it is consumed, the collective agreement (ΣΣΕ) with the real cost of staff, real CAPEX and P&L, break-even and a decision simulator with a GO/NO-GO verdict. Athens · Thessaloniki · Symi. 242 pages, 92 sections and 26 industry voices · Edition 7.

€299
single licence · PDF
View details →
How to Open a Coffee Shop in France · Practical Guide 2026PDF interior
Available
2026 editionFree sample

How to Open a Coffee Shop in France · Practical Guide 2026

A practical, operational playbook, not a market study: the steps, the real numbers and the decision filters to open a café, a bistrot or a coffee shop in France. The three models (traditional bistrot, specialty and take-away), the closed-quota licence III/IV that you don't create but buy, the fonds de commerce that decides viability, the droit au bail and the pas-de-porte, the bail 3-6-9, the dual VAT (10% coffee/food, 20% alcohol), the café presté / contrat brasseur, real CAPEX and P&L, break-even and a decision simulator with a GO/NO-GO verdict and a plan de financement (DSCR). Paris · Lyon · Bordeaux · Lille. 108 pages and 90 sections · Edition 7.

€299
single licence · PDF
View details →
How to Open a Coffee Shop in Portugal · Practical Guide 2026PDF interior
Available
2026 editionFree sample

How to Open a Coffee Shop in Portugal · Practical Guide 2026

A practical, operational playbook, not a market study: the steps, the real numbers and the decision filters to open a café-pastelaria, a specialty coffee shop or a take-away in Portugal. The three models and which one fits, why the pastelaria pays for the business and the bica doesn't (a frozen preço social ~€0.90 that yields no margin), the real barrier that isn't the licence but the premises' planning fitness (the alteração de utilização, which from 3 Aug 2026 becomes a comunicação prévia under DL 108/2026, yet where the PDM and the condomínio still decide) and the renda inflated by tourism and Alojamento Local. The trespasse versus building from scratch, the arrendamento comercial (NRAU), the Delta machine comodato, dual VAT (13% coffee/food, 23% alcohol and cold drinks), IRC, the CCT da restauração, real CAPEX and P&L, break-even and a decision simulator with a GO/NO-GO verdict. Lisbon · Porto · Braga · Coimbra. 101 pages and 89 sections · Edition 7.

€299
individual licence · PDF
View details →
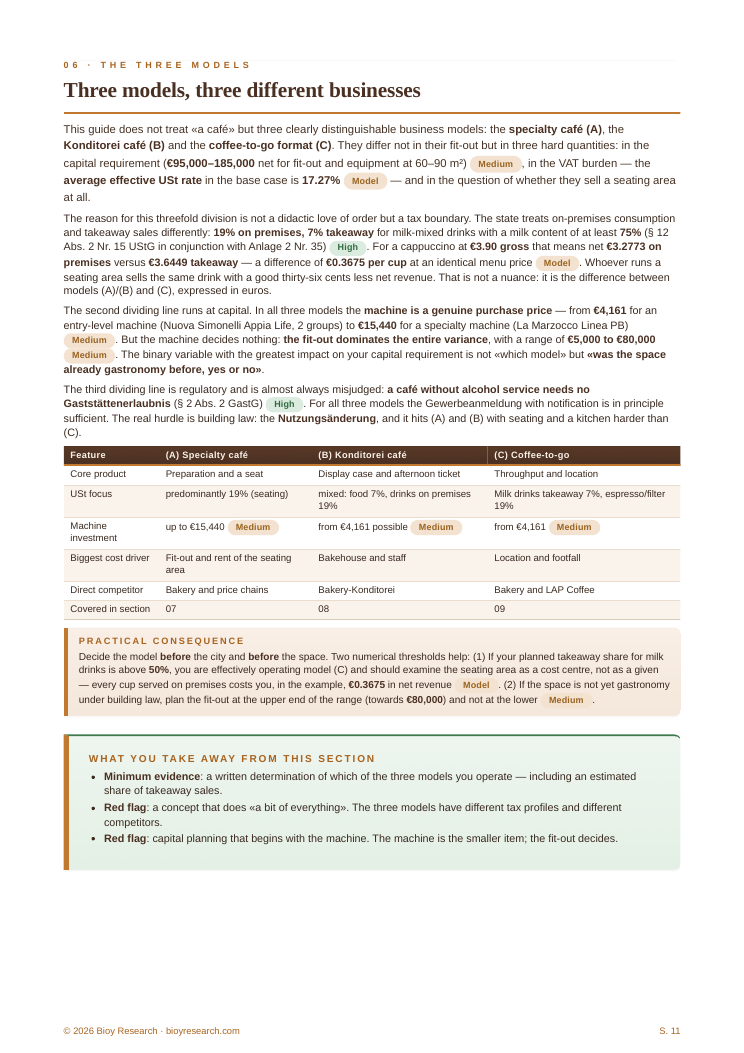
How to Open a Coffee Shop in Germany · Practical Guide 2026PDF interior
Available
2026 editionFree sample

How to Open a Coffee Shop in Germany · Practical Guide 2026

A practical, operational playbook, not a market study: the steps, the real numbers and the decision filters to open a coffee shop in Germany. The three models (specialty café, Konditorei-Café 'Kaffee und Kuchen' and coffee-to-go), the licence you do NOT need (an alcohol-free café needs no Gaststättenerlaubnis) versus the real barrier (the Nutzungsänderung, the change-of-use of the premises), the USt (VAT) that changes within the same cup (19% / 7% depending on the product and the channel, and the plant milk that loses the 7%), the Minijob that is not cheap labour, the Mindestlohn that rises by law on a fixed date, the Gewerbemiete and the Kaffeesteuer hidden in the bean, real CAPEX and P&L, break-even and a decision simulator with a GO/NO-GO verdict. Berlin · Munich · Hamburg · Leipzig. 136 pages, 90 sections and 27 industry voices · Edition 7.

€299
single licence · PDF
View details →
How to open a coffee shop in Spain · Practical guide 2026PDF interior
Available
2026 editionFree sample

How to open a coffee shop in Spain · Practical guide 2026

A practical, operational guide, not a market study: the steps, the real numbers and the decision filters to open a coffee shop in Spain. Permits and licences by city (Madrid, Barcelona, Valencia, Seville), the three deal-killers of the premises (extraction flue, planning compatibility, change of use), real CAPEX (€50,000–€80,000) and P&L, break-even (~€400/day ≈ 80 tickets) and 2026 tax (10% VAT, RETA scheme, €1,221 minimum wage). The Edition 5 highlight is a decision simulator that crosses tickets/day × average ticket and returns a GO/NO-GO verdict with a payback table. 108 pages, 89 sections and 53 quotes from Spanish operators · Edition 5.

€299
individual licence · PDF
View details →
The specialty coffee market in SpainPDF interior
Available
2026 editionFree sample

The specialty coffee market in Spain

Demand, competition, consumer and strategic opportunity. A map of 15 brands with real location counts, density by city and economics. Data 2023–2026.

€299
individual licence · PDF
View details →
The specialty coffee market in GermanyPDF interior
Available
2026 editionFree sample

The specialty coffee market in Germany

Europe's largest specialty market and its leading roasting hub. Channels, competitors by archetype, EUDR traceability and underserved gaps for a new brand, with deep dives into Berlin, Hamburg and Munich. Data 2023–2026.

€299
individual licence · PDF
View details →
The specialty coffee market in ChinaPDF interior
Available
2026 editionFree sample

The specialty coffee market in China

The world's fastest-growing coffee market, split between the ¥9.9 price war (Luckin, Cotti) and the premium end (%Arabica, Manner). For the foreign entrant: WFOE, local partners and deep dives into Shanghai, Beijing, Shenzhen and Chengdu. Data 2023–2026.

€299
individual licence · PDF
View details →
Opening a specialty coffee shop in AndorraPDF interior
Available
2026 editionFree sample

Opening a specialty coffee shop in Andorra

Feasibility study for a first-time founder who wants to open one specialty coffee shop in Andorra and work in it. Four ways in — a take-away counter, an espresso bar, a café with seats and the take-over of an equipped café — are costed in euros under the rules of 2026 and set beside what the official statistics report for restaurants and bars together. The report gives no verdict for any format and says why; it gives instead what each format must take for its owner to be paid, the money to open and the checks to make before signing a lease. It opens with a four-page executive summary and includes the coffee lists that could be read, Andorran and named French and Spanish neighbours, IGI at 4.5 % on what is served against 1 % on what is taken away, the registration threshold and the simplified method, sole trader against SL, the owner's CASS and the income tax, the statutory minimum wage and what an hour of staff costs, the parish's opening licence and activity tax, asked rents, the investment line by line with what could not be priced, a plan with decision gates, the reviews that tried to break the report, and every input traced to its source. Scope: Andorra, base case Andorra la Vella and Escaldes-Engordany · figures in EUR · data as of 18 October 2026 · Edition 9 · in English.

€299
individual licence · PDF
View details →
The specialty coffee market in FrancePDF interior
Available
2026 editionFree sample

The specialty coffee market in France

From the capsule-dominated home to the rise of néocafés: demand, the French consumer, competition by archetype and the economics of entering through Paris, Lyon, Bordeaux and Marseille. Data 2023–2026.

€299
individual licence · PDF
View details →
The specialty coffee market in the NetherlandsPDF interior
Available
2026 editionFree sample

The specialty coffee market in the Netherlands

A mature coffee culture and Europe's re-export hub: home, office and out-of-home channels, competitors by archetype and the opportunity in Amsterdam, Rotterdam, Utrecht and The Hague. Data 2023–2026.

€299
individual licence · PDF
View details →
The specialty coffee market in PortugalPDF interior
Available
2026 editionFree sample

The specialty coffee market in Portugal

Beyond the bica: a tourism-fuelled specialty wave across coffee shops and brunch. Demand, the Portuguese consumer, competition and the economics of entering Lisbon, Porto, Cascais and the Algarve. Data 2023–2026.

€299
individual licence · PDF
View details →
The specialty coffee market in ItalyPDF interior
Available
2026 editionFree sample

The specialty coffee market in Italy

The home of espresso meets the specialty wave: how a deeply rooted €1 coffee culture premiumises. Demand, competition by archetype and the economics of entering Rome, Milan, Florence and beyond. Data 2021–2026.

€299
individual licence · PDF
View details →
The specialty coffee market in the UKPDF interior
Available
2026 editionFree sample

The specialty coffee market in the UK

A mature £6.8bn out-of-home market with a leading independent scene: demand, competition by archetype and the economics of entering London, Manchester and beyond, factoring the National Living Wage and licensing. Data in £, 2023–2026.

€299
individual licence · PDF
View details →
The specialty coffee market in FinlandPDF interior
Available
2026 editionFree sample

The specialty coffee market in Finland

The world's highest per-capita coffee consumption and a deep filter culture ripe for premiumisation. Demand, competition and the economics of entering Helsinki, Tampere, Turku and beyond. Data 2021–2026.

€299
individual licence · PDF
View details →
The specialty coffee market in NorwayPDF interior
Available
2026 editionFree sample

The specialty coffee market in Norway

A world-class specialty scene led by names like Tim Wendelboe and Fuglen, set against high labour costs. Demand, competition and the economics of entering Oslo, Bergen and beyond. Data 2021–2026.

€299
individual licence · PDF
View details →
The specialty coffee market in IcelandPDF interior
Available
2026 editionFree sample

The specialty coffee market in Iceland

A market driven by mass tourism (2.27M visitors vs 389,000 residents) and an all-local scene with no Starbucks. Demand, competition and the economics of entering Reykjavík, the capital region, Akureyri and the tourist nodes. Data 2021–2026.

€299
individual licence · PDF
View details →
The specialty coffee market in LuxembourgPDF interior
Available
2026 editionFree sample

The specialty coffee market in Luxembourg

A small market with the EU's highest disposable income, ~231,000 cross-border workers and a highly international population: demand, a curated scene (~14 cafés and 2 roasters) and the economics of entering Luxembourg City, Esch-sur-Alzette/Belval and secondary nodes. Data 2024–2026.

€299
individual licence · PDF
View details →
The specialty coffee market in BelgiumPDF interior
Available
2026 editionFree sample

The specialty coffee market in Belgium

A European green-coffee hub with a mature, bilingual scene (FR/NL): the TAM is adjusted for its hub function, not direct final consumption. Demand, competitive map and entry economics, with reference specialty operators (MOK, Caffènation, OR Coffee, WAY, Beyers). HORECA agreement CP 302, the March 2026 VAT reform (served coffee at 12%) and EUDR applies. Deep dive of Brussels, Antwerp, Ghent and Leuven. Data 2024–2026.

€299
individual licence · PDF
View details →
Opening a specialty coffee shop in CzechiaPDF interior
Available
2026 editionFree sample

Opening a specialty coffee shop in Czechia

Feasibility study for a first-time founder who wants to open one specialty coffee shop in Czechia and run it personally. Four formats — a to-go window, an espresso bar, a café with food and the take-over of an equipped café — go through one economic engine, sixty months from the opening day. The owner trades as a sole trader, pays social and health insurance and income tax, and that pay is set against the statutory minimum wage and against what the same hours earn in someone else's café. It includes a menu audit of 60 venues read on 2 October 2026, the VAT on coffee in 2026 and under the act signed for 2027, the payroll reproduced to the koruna against a 2026 calculator, agreements (DPP) and what an hour of staff costs, the permits and the premises rules, key money and asking rents from the advertisements in five cities, the investment line by line, the engine set against the accounts of single-site café companies read in the court register, the frontier in receipts a day at which each verdict changes, a stress table, a plan with decision gates, the reviews and the audit that tried to break the report, and every input traced to its source. Scope: Czechia, base case Prague · figures in CZK · data as of 2 October 2026 · Edition 8 · in English.

€299
individual licence · PDF
View details →
Opening a specialty coffee shop in HungaryPDF interior
Available
2026 editionFree sample

Opening a specialty coffee shop in Hungary

Feasibility study for a first-time founder who wants to open one specialty coffee shop in Hungary and run it personally. Four formats — a to-go window, an espresso bar, a café with food and the take-over of an equipped café — go through one economic engine, sixty months from the opening day. The owner trades as a sole trader, on the flat rate while the sales stay under its cap and on the entrepreneur's income tax above it, and the result is set against the statutory minimum wage and against what the same hours earn in someone else's café. It includes a menu audit of 60 venues read on 4 October 2026, the VAT on a coffee at the table and in a paper cup with the tourism development contribution, the question of how a kávézó is classed, the payroll reproduced to the forint against a 2026 calculator, students, pensioners and what an hour of staff costs, the permits and the premises rules, key money and asking rents from the advertisements in five cities, the investment line by line, the engine set against the cost lines of 35 single-site café companies, each listed with the page it was read from, the frontier in receipts a day at which each verdict changes, a stress table, a plan with decision gates, the reviews and the audit that tried to break the report, and every input traced to its source. Scope: Hungary, base case Budapest · figures in HUF · data as of 4 October 2026 · Edition 8 · in English.

€299
individual licence · PDF
View details →
Opening a specialty coffee shop in GreecePDF interior
Available
2026 editionFree sample

Opening a specialty coffee shop in Greece

Feasibility study for a first-time founder who wants to open one specialty coffee shop in Greece and run it personally. Four formats — a take-away shop, an espresso bar, a café with bought-in food and the take-over of an equipped café — go through one economic engine built from costs that can be named, sixty months from the opening day, each on a lean and on a staffed rota. The report gives no verdict for any format and says why: no sales of a comparable shop could be read. It gives instead the sales a year and the takings a day at which each format covers its payments, pays its owner the minimum wage and pays a market wage, the full band of readings, and the money needed to open with the VAT on the build inside. It includes served and to-go prices from cafés' and chains' own lists, 24 % VAT on a drink served and 13 % to go, fourteen salaries under the binding catering agreement and what an hour of staff costs, the sole proprietor's contributions and the presumed minimum income, asking rents from 1,245 advertisements, the investment line by line, a stress table, a plan with decision gates, the reviews and the audit that tried to break the report, and every input traced to its source. Scope: Greece, base case Athens · figures in EUR · data as of 9 October 2026 · Edition 8 · in English.

€299
individual licence · PDF
View details →
The specialty coffee market in SloveniaPDF interior
Available
2026 editionFree sample

The specialty coffee market in Slovenia

Slovenia is a small but high-quality scene: a country of just 2 million people with specialty concentrated in Ljubljana, Maribor and the Coast (Piran, Portorož, Koper), and reference roasters (STOW, Escobar, GOAT STORY, Čokl, Banibeans). The challenge is not volume but consumer education in a traditional market "between two walls", supported by a strong technical community (cuppings, events, the Ljubljana Coffee Festival). Demand, competitive map and entry economics with granular geomarketing by district (footfall, rent €/m², site selection), labour cost (the minimum wage rose +16% in 2026 to €1,481.88/month, with employer charges of 17.10%) and a key tax nuance: served coffee is taxed at 9.5% DDV / reduced VAT (only sugar-sweetened drinks moved to 22% in 2025) and retail beans at 9.5%. Legal forms d.o.o. (€7,500 capital) and s.p. Includes a decision simulator (GO/NO-GO profitability matrix and break-even) and distinctive blocks on food safety/HACCP, EUDR (staggered application 2026-2027) and traceability, packaging and PPWR, and entry feasibility (investment thesis, format, capital and payback). Interviews with verifiable quotes from Slovenian founders (STOW/Turšič, Escobar, Čokl/Buna, Banibeans). EUDR applies as an EU country; eurozone (€). Deep dive of Ljubljana, Maribor and the Coast. Data 2020–2026.

€299
individual licence · PDF
View details →
Opening a specialty coffee shop in RomaniaPDF interior
Available
2026 editionFree sample

Opening a specialty coffee shop in Romania

Feasibility study for a first-time founder who wants to open one specialty coffee shop in Romania and run it personally. Four formats — a to-go kiosk, an espresso bar, a café with brunch and a 5 to go franchise unit — go through one economic engine, sixty months from the opening day, with the ramp of the first years and the season of every month. The owner is paid the way the law allows an SRL to pay its shareholder, and that pay is set against the market value of the owner's own hours. It includes thirty menus read on 29 September 2026, the VAT rate ANAF actually enforces on a cup of coffee, the payroll rules that make a part-timer as dear as a full-timer, the permits and the one consent that can stop a project, the investment line by line, the engine checked against the filed accounts of real Romanian cafés, the frontier in receipts a day at which each verdict changes, a stress table, a 90-day plan with decision gates, the reviews that tried to break the report, and every input traced to its source. Scope: Romania, base case Bucharest · data as of 29 September 2026 · Edition 8 · in English.

€299
individual licence · PDF
View details →
Opening a specialty coffee shop in TurkeyPDF interior
Available
2026 editionFree sample

Opening a specialty coffee shop in Turkey

Feasibility study for a first-time founder who wants to open one specialty coffee shop in Turkey and work in it. Four ways in — a take-away counter, an espresso bar, a café with seats and food and the take-over of an equipped café — are costed in lira under the rules of 2026 and set beside what TurkStat reports for the trade. The report gives no verdict for any format and says why; it gives instead what each format must take for its owner to be paid, the money to open and the checks to make before signing a lease. It opens with a four-page executive summary and includes the specialty menus that could be read, VAT at 10 % on what is sold against 1 % and 20 % on what is bought, sole proprietor against limited company and the owner's Bağ-Kur, the minimum wage of 2026 and what an hour of staff costs, the licence by declaration and its fee by district, two agencies' asked rents in Istanbul, the investment line by line with what could not be priced, a plan with decision gates, the reviews that tried to break the report, and every input traced to its source. Scope: Turkey, base case Istanbul · figures in TRY · data as of 13 October 2026 · Edition 9 · in English.

€299
individual licence · PDF
View details →
Opening a specialty coffee shop in CroatiaPDF interior
Available
2026 editionFree sample

Opening a specialty coffee shop in Croatia

Feasibility study for a first-time founder who wants to open one specialty coffee shop in Croatia and run it personally. Four formats — a take-away shop, an espresso bar, a café with food and the take-over of an equipped café — each sized to the minimum conditions of its type, go through one economic engine, sixty months from the opening day. The owner is a craftsman keeping business books, and the result is set against the statutory minimum wage and against what the same hours earn in someone else's café, with the cash of the month kept apart from the build written off. It includes the price lists of 43 caffe bars and of the two specialty cafés that publish a priced menu, the VAT on drinks and food, the reverse charge on the works, the craft's contributions, the collective agreement extended in 2026 and what an hour of staff costs, the types of establishment and their toilets, asking rents with each advertisement listed, the investment line by line, the engine set against the official statistics of the trade, the frontier in euros of sales and in receipts a day, a stress table, a plan with decision gates, the reviews and the audit that tried to break the report, and every input traced to its source. It gives a verdict for the one format whose sales could be anchored and says plainly why the other three get none. Scope: Croatia, base case Zagreb · figures in EUR · data as of 6 October 2026 · Edition 8 · in English.

€299
individual licence · PDF
View details →
Opening a specialty coffee shop in SerbiaPDF interior
Available
2026 editionFree sample

Opening a specialty coffee shop in Serbia

Feasibility study for a first-time founder who wants to open one specialty coffee shop in Serbia and work in it. Four ways in — a take-away counter or kiosk, an espresso bar, a café with seats and food and the take-over of an equipped café — are costed in the rules enacted for 2027 and set beside what 454 drink-serving companies file with the Business Registers Agency. The report gives no verdict for any format and says why; it gives instead what each format must take for its owner to be paid, the money to open and the checks to make before signing a lease. It opens with a four-page executive summary and includes prices from specialty menus that could be read, 20 % VAT and its threshold, the excise on coffee and fiscalisation, entrepreneur against d.o.o. and why the flat rate is closed to a café, the minimum wage of 2026 and 2027 and what an hour of staff costs, permits and premises, two agencies' asked rents in Belgrade, the investment line by line with what could not be priced, a plan with decision gates, the reviews that tried to break the report, and every input traced to its source. Scope: Serbia, base case Belgrade · figures in RSD · data as of 12 October 2026 · Edition 9 · in English.

€299
individual licence · PDF
View details →
Opening a specialty coffee shop in CyprusPDF interior
Available
2026 editionFree sample

Opening a specialty coffee shop in Cyprus

Feasibility study for a first-time founder who wants to open one specialty coffee shop in Cyprus and run it personally. Four formats — a take-away shop, an espresso bar, a café with food and the take-over of an equipped café — each sized to the licensing criteria, go through one economic engine, sixty months from the opening day. The owner is self-employed, and the result is set against the statutory minimum wage and against what the same hours earn in someone else's café, with the cash of the month kept apart from the build written off. It includes a price audit of 136 venues read on 5 October 2026, the VAT on a coffee at the table and in a cup to go, the reverse charge on the works, the 2026 tax reform and the owner's contributions, the payslip and what an hour of staff costs, the tourism licence, toilets and parking, asking rents in three cities, key money from seventeen businesses for sale listed one by one, the investment line by line, the engine set against the official statistics of cafés and bars, the frontier in receipts a day at which each verdict changes, a stress table, a plan with decision gates, the reviews and the audit that tried to break the report, and every input traced to its source. Scope: Cyprus, base case Nicosia · figures in EUR · data as of 5 October 2026 · Edition 8 · in English.

€299
individual licence · PDF
View details →
Opening a specialty coffee shop in LiechtensteinPDF interior
Available
2026 editionFree sample

Opening a specialty coffee shop in Liechtenstein

Feasibility study for a first-time founder who wants to open one specialty coffee shop in Liechtenstein and work in it. Four ways in — a take-away counter, an espresso bar, a café with seats and food and the take-over of an equipped café — are costed in Swiss francs under the rules of 2026 and set beside what the official statistics report for hotels and restaurants. The report gives no verdict for any format and says why; it gives instead what each format must take for its owner to be paid, the money to open and the checks to make before signing a lease. It opens with a four-page executive summary and includes the coffee lists that could be read, VAT at 8.1 % on what is served against 2.6 % on what is carried out, the effective and net-tax-rate methods, sole proprietor against GmbH, the owner's AHV and the national income tax with the municipal surcharge, the employers' wage list and what an hour of staff costs, the hospitality licence and exam, change of use and parking in Vaduz, asked rents, the investment line by line with what could not be priced, a plan with decision gates, the reviews that tried to break the report, and every input traced to its source. Scope: Liechtenstein, base case Vaduz and Schaan · figures in CHF · data as of 15 October 2026 · Edition 9 · in English.

€299
individual licence · PDF
View details →
Opening a specialty coffee shop in SwedenPDF interior
Available
2026 editionFree sample

Opening a specialty coffee shop in Sweden

Feasibility study for a first-time founder who wants to open one specialty coffee shop in Sweden and work in it. Four formats — a take-away shop, an espresso bar, a café with seating and food and the take-over of an equipped café — go through one economic engine tied to the filed annual accounts of 367 small Swedish café companies, 277 once those describing another trade are removed, and measured on the owner's money over sixty months. The report opens with a four-page executive summary: the answer for each format with its interval, the money to open, the sales needed in kronor and in receipts a day, the assumptions that carry the result and the three checks to make before signing. It includes prices from cafés' own lists, 12 % VAT on a drink served and 6 % to go until 31 December 2027, wages under the Visita–HRF collective agreement in a country with no statutory minimum wage and what an hour of staff costs, sole trader against limited company, permits and their calendar in Stockholm, stated rents, the investment line by line, stress rows, a plan with decision gates, the reviews that tried to break the report, and every input traced to its source. Scope: Sweden, base case Stockholm · figures in SEK · data as of 11 October 2026 · Edition 9 · in English.

€299
individual licence · PDF
View details →
Opening a specialty coffee shop in AustriaPDF interior
Available
2026 editionFree sample

Opening a specialty coffee shop in Austria

Feasibility study for a first-time founder who wants to open one specialty coffee shop in Austria and run it personally. Four formats — a to-go window, an espresso bar, a café with food and the take-over of an equipped café — go through one economic engine, sixty months from the opening day. The owner trades as a sole trader, pays social insurance and income tax, and that pay is set against what the same hours earn under the collective agreement. It includes seventeen specialty menus read in September and October 2026, the VAT rate Austria applies to every coffee drink, the payroll reproduced to the cent against the Finance Ministry's calculator, the eight-place line that decides which permits a founder needs, key money and rents from the advertisements, the investment line by line, the engine set against the sector benchmark, the frontier in receipts a day at which each verdict changes, a stress table, a plan with decision gates, the reviews and the independent audit that tried to break the report, and every input traced to its source. Scope: Austria, base case Vienna · data as of 1 October 2026 · Edition 8 · in English.

€299
individual licence · PDF
View details →
Opening a specialty coffee shop in PolandPDF interior
Available
2026 editionFree sample

Opening a specialty coffee shop in Poland

Feasibility study for a first-time founder who wants to open one specialty coffee shop in Poland and run it personally. Four formats — a to-go window, an espresso bar, a café with food and the take-over of an equipped café — go through one economic engine, sixty months from the opening day. The owner trades as a sole trader, pays social insurance, the health contribution and income tax, and that pay is set against the statutory minimum wage and against what the same hours earn in someone else's café. It includes a menu audit of 34 venues read on 2 October 2026, the VAT rate Poland applies to every coffee drink and to food eaten in and taken away, the payroll reproduced to the grosz against a 2026 calculator, the mandate contract for students and the labour-inspectorate reform in force since 8 July 2026, the sanitary approval and the premises rules, key money and asking rents from the advertisements in five cities, the investment line by line, the engine set against the filed accounts of Polish café companies, the frontier in receipts a day at which each verdict changes, a stress table, a plan with decision gates, the reviews and the independent audit that tried to break the report, and every input traced to its source. Scope: Poland, base case Warsaw · figures in PLN · data as of 2 October 2026 · Edition 8 · in English.

€299
individual licence · PDF
View details →
Opening a specialty coffee shop in DenmarkPDF interior
Available
2026 editionFree sample

Opening a specialty coffee shop in Denmark

Feasibility study for a first-time founder who wants to open one specialty coffee shop in Denmark and work in it. Four ways in — a take-away window, an espresso bar, a café with seats and food and the take-over of a running shop — are read against what 62 single-shop coffee companies file with the Danish Business Authority: gross profit, staff costs, depreciation and result, by size of shop. The report opens with a four-page executive summary: the answer for each size of shop with its spread, the money to open and what stays unpriced, what the shop must earn, the assumptions that carry the result and the three checks to make before signing. It includes prices from coffee bars' own menus, the single 25 % VAT and the coffee duty still in force, pay in a country with no statutory minimum wage and what an hour of staff costs, sole proprietorship against ApS, permits and their calendar in Copenhagen, stated rents, the lease and what it binds, the investment line by line, asking prices of running shops, a plan with decision gates, the reviews that tried to break the report, and every input traced to its source. Scope: Denmark, base case Copenhagen and Frederiksberg · figures in DKK · data as of 10 October 2026 · Edition 9 · in English.

€299
individual licence · PDF
View details →
The athletic footwear market in EuropePDF interior
Available
2026 editionFree sample

The athletic footwear market in Europe

Size, consumer, competition and strategic opportunity. SOM with Monte Carlo triangulation, brand financial profiles, pricing and economics by channel. Data 2023–2026.

€299
individual licence · PDF
View details →
The specialty coffee market in BrazilPDF interior
Available
2026 editionFree sample

The specialty coffee market in Brazil

The world's largest coffee producer is living an expanding urban third wave. Demand, competitive map and entry economics, with a district-by-district read of São Paulo. Origin advantage (high-quality local bean), taxation and labour cost, and the opportunity of a roastery-café with a terroir story. Data 2024–2026.

€299
individual licence · PDF
View details →
The specialty coffee market in ColombiaPDF interior
Available
2026 editionFree sample

The specialty coffee market in Colombia

A coffee-growing country par excellence where domestic specialty consumption is growing fast. Demand, competitive map and entry economics, with a read of Bogotá by neighbourhood and of Medellín. Origin advantage, taxation and labour cost, and the entry plan for a roastery-café with an origin story. Data 2024–2026.

€299
individual licence · PDF
View details →
The specialty coffee market in EcuadorPDF interior
Available
2026 editionFree sample

The specialty coffee market in Ecuador

An emerging, dollarized market with its own production and a young specialty scene in Quito and Guayaquil. Demand, competitive map and entry economics. The paradox of a producer that imports commodity coffee, taxation and labour cost, and the entry plan for a roastery-café. Data 2024–2026.

€299
individual licence · PDF
View details →
The specialty coffee market in IrelandPDF interior
Available
2026 editionFree sample

The specialty coffee market in Ireland

A mature scene in Dublin with margins under pressure: cost, not demand, is the threat. Demand, competitive map and entry economics, with a district-by-district read of Dublin. HORECA VAT at 9%, labour cost, EUDR applies and the entry plan modelled with a buffer. Data 2024–2026.

€299
individual licence · PDF
View details →
The specialty coffee market in PeruPDF interior
Available
2026 editionFree sample

The specialty coffee market in Peru

A producing country with a booming specialty scene in Lima. Demand, competitive map and entry economics, with a district-by-district reading of Lima. Origin advantage (award-winning Peruvian beans), taxation and labour cost, and the entry plan for a roastery-café built on an origin story. Data 2024–2026.

€299
individual licence · PDF
View details →
The specialty coffee market in SwitzerlandPDF interior
Available
2026 editionFree sample

The specialty coffee market in Switzerland

The most expensive market in the world, with premium demand and a labour cost that defines the margin. Demand, competitive map and entry economics, with a reading of Zurich by Kreise. Swiss VAT (8.1% / 2.6% takeaway), L-GAV labour cost and the entry plan of a roastery-café. Data 2024–2026.

€299
individual licence · PDF
View details →
The specialty coffee market in ChilePDF interior
Available
2026 editionFree sample

The specialty coffee market in Chile

An emerging market where specialty coffee is growing against a historical habit of tea and instant coffee. Demand, competitive map and entry economics, with a read of Santiago by district and the touristic south. The real barrier of imported green coffee, 19% VAT and the Pro Pyme regime, the REP packaging law and EUDR (does not apply except for exports to the EU). Data 2024–2026.

€299
individual licence · PDF
View details →
The specialty coffee market in UruguayPDF interior
Available
2026 editionFree sample

The specialty coffee market in Uruguay

The land of mate: specialty coffee grows against a deeply rooted habit of mate and infusions (142 cups/year per capita, 54% of the market still instant). Demand, competitive map and entry economics, with a read of Montevideo by neighbourhood (Pocitos, Punta Carretas, Cordón, Ciudad Vieja) and the emerging frontier. Uruguay imports all of its coffee, 22% VAT on served coffee and 10% on retail beans, EUDR (does not apply unless exporting to the EU). 2024–2026 data · Edition 4.

€299
individual licence · PDF
View details →
The specialty coffee market in ParaguayPDF interior
Available
2026 editionFree sample

The specialty coffee market in Paraguay

An early-stage market where specialty coffee grows against the deep-rooted habit of tereré (81.6% urban penetration) and mate cocido. Per-capita consumption is very low but imports are surging (+71.8% in 2025), with cold brew as the entry lever driven by the hot climate. Demand, competitive map and entry economics in Asunción, with 10% VAT, IPS payroll costs and municipal + INAN licensing. EUDR does not apply unless exporting to the EU. Edition 4 with source traceability and a bottom-up market model. Data 2024–2026.

€299
individual licence · PDF
View details →
Specialty coffee capsules · Spain and sales into the EU · Decision report on system, industrial property, manufacturing, channel and viabilityPDF interior
Available
2026 editionFree sample

Specialty coffee capsules · Spain and sales into the EU · Decision report on system, industrial property, manufacturing, channel and viability

Decision report for the Spanish specialty roaster weighing whether to launch a capsule of its own, with three routes run through the same engine: outsourcing to a co-packer, buying an in-house line, or manufacturing for third parties. The question that governs everything is not «is there room for one more capsule on the shelf?», but «can a specialty roaster sell its own capsule, and through which channel?». It includes an original, reproducible shelf audit —150 capsule SKUs counted one by one through the catalogue APIs of Mercadona, Dia and Consum on 3 August 2026, plus 102 references from the system owner's direct channel, with the scope declared in full: Carrefour, El Corte Inglés, Alcampo, Eroski and Lidl blocked access and are not audited—, the industrial property map that separates what lapsed in 2012 from what is still alive (25 Nestlé patents validated in Spain and in force to 2033-2043, with their subject matter and their expiry), what Regulation (EU) 2025/40 does and does not require of a rigid capsule from 12 February 2028, a tax risk whose legal basis changed on 12 August 2026, the physics of the format —dose, degassing, residual oxygen, barrier, and what separates the shelf life printed on the box from sensory shelf life—, unit economics with the pack and the coffee weighed separately, and the comparison between contract filling and an owned line. With a reproducible calculation engine of 65 assumptions traced to source and confidence level, three archetypes × three scenarios, sensitivities, four declared gaps rather than filled ones —none of the nine verified co-packers publishes a contract-filling rate— and an adversarial review that attacks the report's own thesis. Scope: Spain and the European Union. 2026 data · Edition 7.

€3,499
single licence · PDF
View details →
Coffee cart and food truck · Spain · Decision report on permits, unit format, service capacity, diary of dates and viabilityPDF interior
Available
2026 editionFree sample

Coffee cart and food truck · Spain · Decision report on permits, unit format, service capacity, diary of dates and viability

Decision report for the entrepreneur or small business considering setting up a mobile coffee unit in Spain —cart, tricycle, trailer or van— and about to turn their savings into the vehicle before knowing whether they will be allowed to serve at all. The question that governs the work is not «where do I stand and how much do I pay?», but «is there anywhere I will be authorised to serve prepared coffee, how many trading days a year can I actually fill, and is what is left after paying myself for every hour money, or an accounting illusion?». It includes the named audit of the venta ambulante (street trading) by-law and the public-domain occupation regime of eight municipalities read one by one —Madrid, Barcelona, Valencia, Seville, Málaga, Zaragoza, Bilbao and San Sebastián/Donostia, with a cut-off of 4 August 2026—, with the unaudited universe declared in every sentence: Spain has more than 8,100 municipalities and the rest have not been read. It brings the pitch fee measured by actual auction rather than by reserve price —in the same tender and on the same day in Zaragoza, a site with a €23,900 reserve was awarded at €72,014 with fifteen bids while another at €5,600 closed at €6,000 with one—, the physics of the format with the two constraints that are not negotiable (the 750 kg maximum authorised mass, weighed with the tanks full and not unladen, and the architecture of the espresso machine as against its number of groups), the three capacity magnitudes almost nobody distinguishes —sustained rate, fifteen-minute burst and peak-hour capacity— and the curve that turns drinks demanded into drinks served, IVA (Spanish VAT) with its two rates on a mixed menu, RETA 2026 (Spain's self-employed social security scheme) closed against the BOE, and the economics of a business that turns out to depend on the calendar rather than on footfall. Five operating archetypes run through the same engine —private land, public highway, events, recurring corporate and seasonal— with their CAPEX built line by line, their annual result, their net present value and the euros per hour left to the owner, with the eleven-hour door-to-door working day deducted at gross employer cost before any talk of return. Reproducible calculation engine with 99 assumptions traced one by one to their source, their date and their confidence grade, a tornado of twelve levers moved ±20%, eleven risks with indicator and threshold, three gaps declared rather than filled —nobody in Spain publishes how many coffees a cart sells in a day, and a counting protocol is delivered instead— and an adversarial section that opens by knocking down eight of the report's own statements. Scope: Spain. 2026 data · Edition 7.
€3,499
single licence · PDF
View details →
Coffee tastings and workshops · Spain · Decision report on pricing, experience families, occupancy, legal fit and viabilityPDF interior
Available
2026 editionFree sample

Coffee tastings and workshops · Spain · Decision report on pricing, experience families, occupancy, legal fit and viability

Decision report for the speciality roaster or coffee shop ALREADY trading in Spain —with premises, coffee, machine and a customer base— considering adding a line of experiences: tastings, workshops and events. It is not written for anyone setting up a coffee academy from scratch, and the report excludes that reader expressly on its first page. The question that governs the work is not «what do I charge for a tasting?», but «how many seats do I have to fill at each session for it to pay the hour of whoever runs it, and how many sessions a year will my customer base actually take?». It rests on an audit of our own: 34 prices from 16 Spanish operators verified one by one on each operator's website, with the full table published in the annexe so the reader can redo any median themselves, and with what could NOT be verified declared in that same table: the VAT treatment is stated in only 13 of the 34 prices, and 22 of the 28 operators located publish no calendar. It separates seven families of experience —introductory tasting, comparative tasting, filter brewing workshop, espresso and latte art workshop, roasting experience, corporate event and tourist experience— and analyses each one on its own, because averaging their prices produces a ticket that corresponds to no real session. Six operator archetypes are run through the same engine, each with its contribution per session, its break-even and its annual result, with break-even resolved in the two magnitudes almost nobody distinguishes: the average across the year and the target for each individual session. It brings the legal chapter with the public liability insurance obligation cited under the article of the regional act that imposes it, capacity and licensing, allergen information, the right of withdrawal and its exceptions, and the applicable VAT rate —the report's tax finding: which rate applies is not self-evident, and the report explains why—. Reproducible calculation engine with 65 assumptions declared one by one with their evidence type, source level, date and confidence grade, of which 16 are flagged as low confidence with each one named; a tornado of levers moved ±20%, a year-by-year P&L separating accounting result from cash, and full sensitivity to occupancy. The adversarial section commissioned the refutation of the report's own verdict BEFORE the chapters were written, and that refutation knocked down all four figures of the provisional verdict: the chapter documents what had been got wrong and why, with the corrected figures. Nine successive external reviews and eleven automated guardians that check every published statement against the engine. Scope: Spain. 2026 data · Edition 8.

€990
single licence · PDF
View details →
Ready-to-drink canned coffee · Spain and export to the EU · Decision report on formulation, industrial process, packaging, distribution and viabilityPDF interior
Available
2026 editionFree sample

Ready-to-drink canned coffee · Spain and export to the EU · Decision report on formulation, industrial process, packaging, distribution and viability

Decision report for the roaster or coffee brand that wants its own can, the drinks brand or functional startup born as a ready-to-drink product, and anyone weighing whether to manufacture private label for a retail chain. The question that governs everything is not «is there room for one more cold coffee on the shelf?», but «which product can you actually manufacture, and how far is it from what the Spanish market buys?». It includes an original, reproducible shelf audit —422 products walked through the catalogues of the two chains, with their price, their format and their position—, the identification mark of nine brands read to establish the plant that actually fills each one, the microbiological safety of a low-acid food that tastes acidic and is not (pH measured, the 4.6 threshold, spore-formers and why the real heat treatment is an order of magnitude above the botulinum minimum), the map of who can manufacture in Spain and who cannot, the can as a costing line (slim versus sleek format, minimum print run, BPA-free lacquer with its deadline already passed), the full cascade from shelf price to manufacturer revenue with trade investment inside it, the legal and labelling framework —a caffeine warning that depends on the commercial name, the composite product regime, a VAT rate that decides the recipe— and a dedicated chapter on intra-EU export with the country-by-country matrix of deposits and prior registrations. With a reproducible calculation engine, sensitivity on rotation and drop size, and an adversarial review that attacks the report's own thesis. Scope: Spain and the European Union. 2026 data · Edition 7.

€3,499
single licence · PDF
View details →
Barista and home-coffee accessories shop · Spain · Decision report on range, pricing, unit economics, business archetypes and the legal frameworkPDF interior
Available
2026 editionFree sample

Barista and home-coffee accessories shop · Spain · Decision report on range, pricing, unit economics, business archetypes and the legal framework

Decision report for anyone weighing whether to open a coffee accessories shop —online, bricks-and-mortar, or as a corner inside a business already trading— and for the roaster or coffee shop assessing whether to add a shelf of accessories. The question that governs everything is not «is there demand for speciality coffee?», but «what is left of an average €48 order once you have paid for the product, the carrier, the payment gateway and the returns?». It includes an original audit of the range and prices of the genuinely Spanish competition, with the consultation date and the price seen on screen —preceded by the screening of which shops are really Spanish and which only look it—, the full cascade of an average order line by line with carrier, gateway and returns costs verified for 2026, twelve real products modelled one by one with their chargeable weight and their contribution, five business archetypes each with its own break-even, its five-year profit and loss account and three scenarios, the complete legal framework —general product safety and the product information duty almost nobody meets, food-contact materials, electrical appliances and their reverse logistics, packaging, right of withdrawal and legal guarantee, with the articles cited—, what changes if you import directly (duties by tariff heading, the anti-dumping duty on Chinese ceramics and the flat low-value consignment charge in force since July 2026), and a matrix of eleven risks with early indicator, alert threshold, mitigation, owner and residual risk. With 105 assumptions traced one by one to their source, their date and their confidence level, three adversarial reviews published in full —including the corrections that forced the engine to be rebuilt, with the old figures alongside the new ones— and a reproducible calculation engine in which every published figure names the function that produces it. Scope: Spain. 2026 data · Edition 8.

€990
single licence · PDF
View details →
eSIM for tourists · Reselling from Spain · Decision report on reseller margins, the CNMC operator regime, wholesale opacity and acquiring a customer who buys oncePDF interior
Available
2026 editionFree sample

eSIM for tourists · Reselling from Spain · Decision report on reseller margins, the CNMC operator regime, wholesale opacity and acquiring a customer who buys once
Decision report for the digital entrepreneur, travel agency, price comparison site or tourism business considering reselling data eSIMs under its own brand from Spain. It is not a guide to how eSIM technology works: it is the file on which the decision to commit money is made, and on which of the six ways of building it. Six models —own-brand storefront, mobile app, single-corridor specialist, white label for a tourism business, corporate account and affiliation— run through one and the same economic engine, with the full funnel of the Spanish outbound market: of all trips abroad by residents in Spain, 63.3% go to a country where roaming already comes included in the traveller's own mobile plan, and the market left outside the EU is 6.67 million trips (Eurostat 2024). It includes an audit of our own of Airalo and Holafly prices read on screen across eight destinations on 11 August 2026, the map of fourteen competitors that turn out to be three different businesses, the only public wholesale rate that could be located against fifteen wholesalers who answer only «open an account», the CNMC regime —reselling eSIMs in your own name obliges you to register in the Operators Register under article 6.2 of Act 11/2022, with the doctrine cited and enforcement proceedings opened in July 2026 against an operator in the sector—, the VAT place of supply governed by the SIM's code, a five-year account with three scenarios, a sensitivity tornado, reconciliation with cash, an adversarial chapter with the errors its own reviews uncovered, and 87 parameters traced with source, date and confidence grade. Scope: Spain · 2026 data · Edition 8.

€990
single licence · PDF
View details →
Methodology

Rigorous analysis, built to decide

Every report is built on verified primary sources and turned into readings you can act on. This is the standard we work to, and you can check it in the PDF itself.

No inflated figures

When a figure is an estimate, we say so. Every number is triangulated and comes with its source and confidence level.

A concrete competitive view

Brand by brand, by name: how many locations, where they operate, whether they roast and their real size from public registries.

We don't describe the sector: we settle the decision

A market report tells you how fast a sector is growing. Ours tells you whether this particular decision returns the money, and the conditions under which it stops doing so.

See the ED7 standard we work to →

Clear pricing

The analysis you need, at an accessible price

Each report combines the depth of market intelligence with a direct format and a price made for decision-makers. Here's what it includes.

Premium sector report

USD 2,000–4,750
Extensive reports focused on market size and its evolution, with deep macro-level detail.

Bioy Research report

€299 – 3,499
Decision-focused analysis: competitive map, density by city, economics and entry insight.

Bespoke study

€1,500–6,000
Tailored analysis for one specific site, with an on-site visit and a custom quote.

Let's talk

Support for your purchase, a general enquiry or a report on demand. Write to us and we'll reply.